Annuities · Florida
Compare Annuity Options
Protect your savings from market losses and explore guaranteed income options, with guidance from a licensed, independent Florida agent, at no cost to you.
✓ Compare fixed, MYGA and fixed indexed annuity rates
✓ See options from multiple top-rated insurance companies
✓ No cost and no obligation to buy anything
Takes about a minute. No cost or obligation. Florida License W472056.
Roger Fishel
Independent, licensed annuity specialist. 20+ years helping Florida retirees.
Savings
Income
Companies
Licensed Agent
Annuity Basics
What Is an Annuity and How Does It Work?
Short answer: An annuity is a contract with an insurance company. You pay in a lump sum or a series of payments, your money grows tax-deferred, and the insurer can later turn it into guaranteed income for a set period or for the rest of your life. Fixed and fixed indexed annuities also protect your principal from stock market losses.
Accumulation phase. Your money earns a guaranteed rate (fixed and MYGA) or interest linked to a market index with a 0% floor (fixed indexed).
Income phase. When you are ready, you can take withdrawals or turn on guaranteed lifetime income, much like creating your own pension.
Liquidity. Most contracts let you withdraw about 10% a year without a charge. Larger withdrawals during the surrender period may cost a fee.
Read the full guide: Annuities in Florida Retirement Planning →
Compare Your Options
Types of Annuities Compared
Each type of annuity does a different job. Here is how the main options compare so you can see which one fits your goal.
| Annuity type | Best for | How it grows or pays | Principal protected from market loss? |
|---|---|---|---|
| Multi-Year Guaranteed Annuity (MYGA) | Safe, CD-like growth | Guaranteed fixed rate for a set term, often 3 to 10 years | Yes |
| Fixed Indexed Annuity (FIA) | Growth potential with no market losses | Interest linked to an index, limited by caps or participation rates, with a 0% floor | Yes |
| Immediate Annuity (SPIA) | Income starting now | Lump sum turned into guaranteed payments that begin within a year | Yes, paid out as income |
| Deferred Income Annuity (DIA) | Planned future income | Pay in today, guaranteed income starts at a future date you choose | Yes, paid out as income |
| Lifetime Income Rider | A paycheck you cannot outlive | Optional benefit on many annuities that guarantees lifetime withdrawals | Income is guaranteed; rider fees may apply |
MYGA vs. CD
Fixed Annuity (MYGA) vs. Bank CD
A multi-year guaranteed annuity (MYGA) is often called the CD of the insurance world. Here is how they differ.
| Feature | Fixed annuity (MYGA) | Bank CD |
|---|---|---|
| Rate | Guaranteed for the full term | Guaranteed for the full term |
| Taxes on interest | Tax-deferred until withdrawn | Taxed every year, even if not withdrawn |
| Typical terms | 2 to 10 years | 3 months to 5 years |
| Access to money | Usually up to 10% a year free; surrender charges on more | Early withdrawal penalty, often months of interest |
| Protection | Backed by the insurer, plus Florida guaranty association up to $250,000 | FDIC insured up to $250,000 per depositor, per bank |
| At the end of the term | Renew, take income, or move it tax-free with a 1035 exchange | Renew or cash out, with interest already taxed |
Florida Consumer Protections
How Florida Protects Annuity Owners
Florida has some of the strongest annuity consumer protections in the country, especially for buyers age 65 and older.
| Protection | What it means for you |
|---|---|
| 21-day free look (age 65 and older) | You can cancel a new annuity within 21 days for a refund, as set by Florida law. |
| Surrender charge limits (age 65 and older) | Surrender charges can be no more than 10% and must be gone after the 10th contract year. |
| Suitability rules | Agents must have reasonable grounds to believe an annuity is suitable for you before recommending it. |
| Guaranty association | Up to $250,000 in cash surrender value per owner, per insurer, if an insurance company fails. |
| No state income tax | Florida does not tax annuity income. Federal income tax still applies to earnings. |
Sources: Florida Statutes section 627.4554 and the Florida Life & Health Insurance Guaranty Association. Guaranty association coverage is not a reason to buy an annuity; guarantees depend on the claims-paying ability of the issuing insurer.
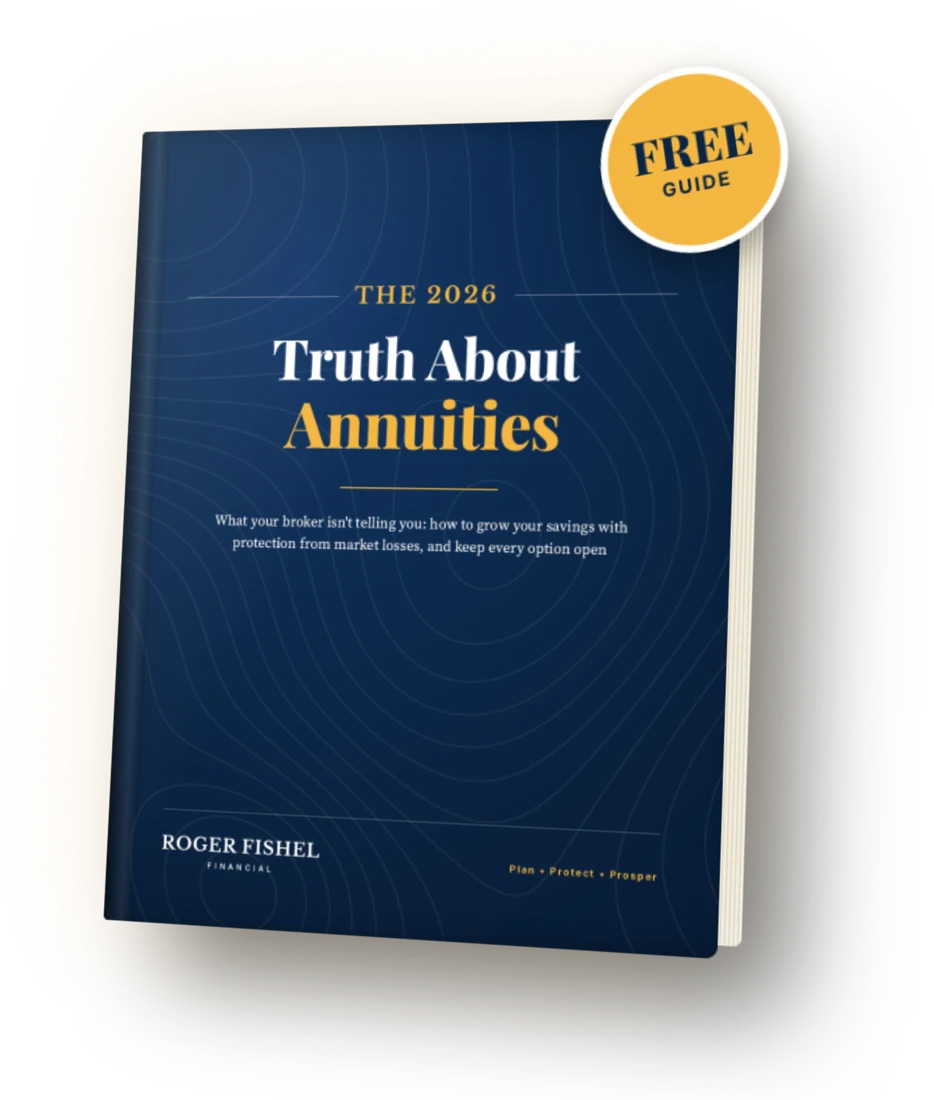
Free guide
The 2026 Truth About Annuities
Learn how annuities can help grow your savings with protection from market losses, and how to keep every option open. Plain English, written by Roger for Florida retirees.
✓ How fixed indexed annuities can grow without market losses
✓ When an annuity may fit your plan, and when it may not
✓ Your choices at the end of the term, including income or not
Free PDF, no cost or obligation.
Free Annuity X-Ray
Own an Annuity? Find Out What It Is Really Doing for You
If you bought an annuity a few years ago and have not looked at it since, it is worth checking. Rates, fees, benefits and options have changed a lot. With our free Annuity X-Ray, we review the annuity you already own and show you:
✓ What you are paying: fees, rider charges and spreads
✓ How it is performing: crediting rates, caps and participation rates
✓ Your surrender charges: the schedule and when they end
✓ Your guarantees: income, death benefit and principal protection
✓ Your options: keep it, turn on income, or exchange it tax-free
There is no cost, no pressure and no obligation to make any changes.
Request My Free Annuity X-RayIs It Time for a Review?
5 Signs Your Annuity Needs an X-Ray
You Bought It Years Ago
If your annuity is 3 or more years old, today's rates and features may be very different from what you have.
You Are Not Sure What You Pay
Many annuity owners cannot name their fees or rider charges. Variable annuities in particular can cost 2% to 3% or more a year.
Your Surrender Period Is Ending
When surrender charges end, you may be free to move your money to a better rate or better income without a penalty.
Your Renewal Rate Dropped
Some contracts start with an attractive rate and then renew much lower. An X-Ray shows what you are earning now.
You Pay for an Income Rider You Do Not Use
Income riders can be valuable, but only if they fit your plan. If not, you may be paying for a benefit you will never use.
Get a Second Opinion Before You Sign
Been offered a new annuity? We will review the illustration, fees and surrender schedule with you for free before you commit.
Request a Free Second Opinion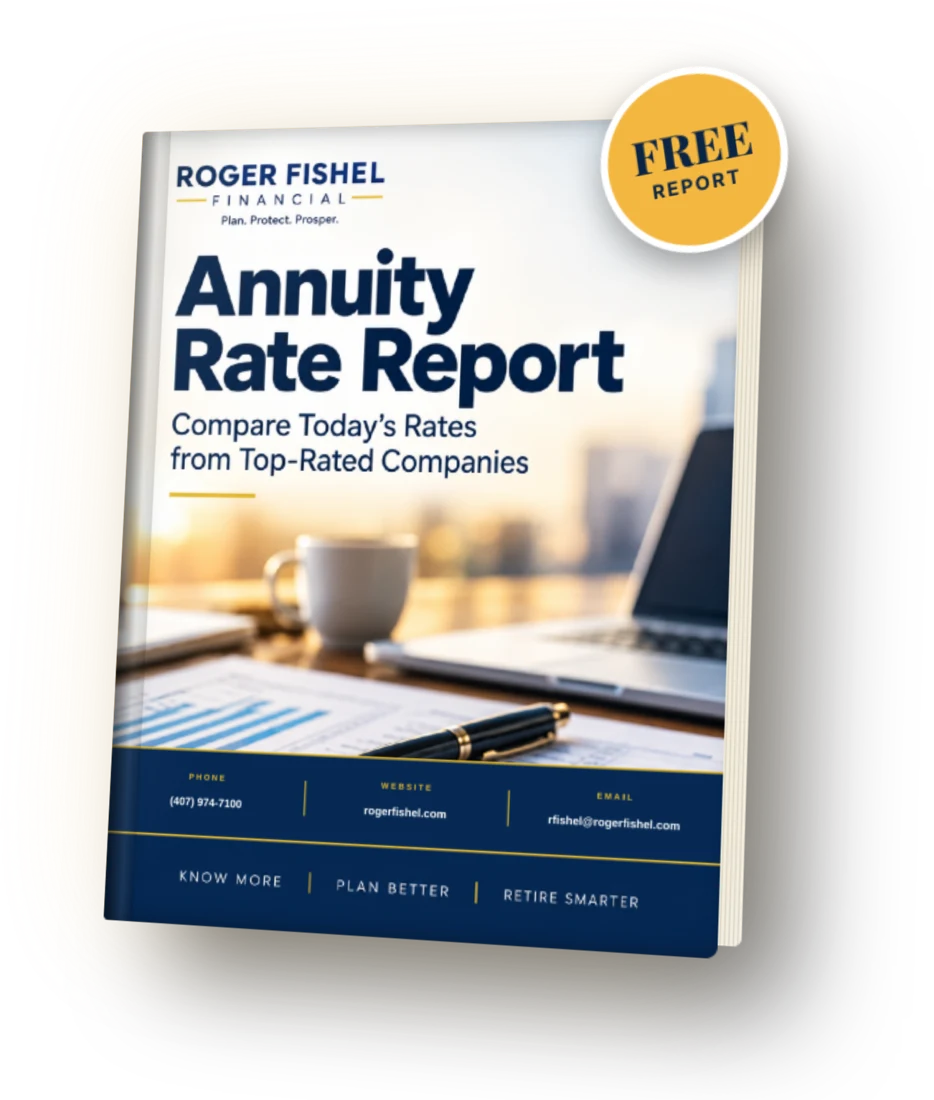
Free Annuity Rate Report
See Today's Top Annuity Rates Before You Decide
Annuity rates change often and can vary widely between companies for similar contracts. Our free Annuity Rate Report helps you shop smarter:
✓ Compare current fixed, MYGA and indexed annuity rates
✓ Review top-rated insurance companies side by side
✓ See how guaranteed annuity rates compare to CDs
✓ Learn the questions to ask before you sign anything
No cost. No obligation. Rates are subject to change and vary by company, term, amount and state.
How It Works
Your Free Annuity Review in Three Simple Steps
No cost, no pressure and no obligation to buy or change anything.
01
Book a Time
Choose a 25-minute time that works for you, by phone, video or in person in Orlando.
02
We Do the Homework
We X-Ray your current annuity or compare rates and features from multiple top-rated insurance companies.
03
Decide With Confidence
You get a clear, plain-English summary of your options. The decision is always yours.
Questions first? Call (407) 974-7100
Why Roger Fishel Financial
Work With a Local, Independent Annuity Specialist
We are not captive to one insurance company, so our job is to find what fits you, not to sell a particular product. And we look at your annuity as one piece of your full retirement plan.
✓ Rates and features compared across multiple top-rated carriers
✓ Plain-English explanations of fees, caps and surrender charges
✓ Annuities coordinated with Social Security, taxes and your income plan
✓ Meet in person in Orlando or by video from anywhere
✓ Ongoing yearly reviews after you buy
Avoid Costly Errors
Common Annuity Mistakes to Avoid
Buying on the Headline Rate
A high first-year bonus or teaser rate can hide low renewal rates, long surrender periods or high rider fees.
Locking Up Too Much Money
Keep enough outside the annuity for emergencies. Most contracts only allow about 10% a year without a charge.
Ignoring Fees and Riders
Rider and administrative fees add up. Know exactly what you pay and what you get for it.
Surrendering Too Early
Cashing out during the surrender period can cost thousands. Timing a move around the surrender schedule matters.
Never Reviewing It Again
Rates, riders and your goals change. A yearly review keeps your annuity working for you.
Get the Annuity Do's and Don'ts Guide
Learn the biggest annuity mistakes and the questions to ask before you move any money. Free download.
Get the Do's and Don'ts GuideOr read the free guide, The 2026 Truth About Annuities.
Keep Learning
More Guides for Florida Retirees
Annuity vs. Bond Ladder
Two ways to build guaranteed retirement income, compared for Florida retirees.
Read the comparison →Annuities in Florida Retirement Planning
When annuities make sense, when they do not, and how to use them well.
Read the guide →Pension Lump Sum vs. Monthly Payments
How to decide, and when an annuity can recreate a pension on your terms.
Read the article →Why Retirees Run Out of Money
The real risks that derail a Florida retirement and how guaranteed income helps.
Read the article →
Frequently Asked Questions
Annuity Questions, Answered
Straight answers to the questions Florida retirees ask us most about annuities.
What is an Annuity X-Ray?
An Annuity X-Ray is a free review of an annuity you already own. We show you what you are paying in fees and rider charges, how the contract is performing, your surrender charge schedule, and exactly what income, death benefit and principal guarantees you have. There is no cost and no obligation to make any changes.
What are today's best annuity rates?
Annuity rates change frequently and vary by company, term length, deposit amount and state. Multi-year guaranteed annuities (MYGAs) often pay more than bank CDs of a similar term. Our free Annuity Rate Report shows current rates from top-rated companies so you can compare before you decide.
Are annuities safe in Florida?
Fixed and fixed indexed annuities protect your principal from market losses, and their guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Florida also has a guaranty association that protects annuity owners up to $250,000 in cash surrender value per owner, per insurer, if a company fails.
Can I lose money in an annuity?
Fixed and fixed indexed annuities do not lose value because of stock market declines. You can lose money by surrendering early and paying surrender charges, and variable annuities can lose value because they are invested in the market.
What is the difference between a MYGA and a fixed indexed annuity?
A MYGA pays a guaranteed interest rate for a set number of years, similar to a CD. A fixed indexed annuity credits interest based on a market index, subject to caps or participation rates, with a 0% floor so you never lose value when the index falls.
How are annuities taxed in Florida?
Florida has no state income tax. At the federal level, earnings grow tax-deferred until withdrawn, and withdrawals of earnings are taxed as ordinary income. Withdrawals before age 59 and a half may also face a 10% federal penalty.
What are annuity surrender charges?
Surrender charges are fees for withdrawing more than the free amount, often about 10% a year, during the first several years of the contract. In Florida, annuities sold to buyers 65 or older cannot charge more than 10% and must have no surrender charge after the 10th year.
Can I move my old annuity without paying taxes?
Often, yes. A 1035 exchange lets you move from one annuity to another without paying taxes on the gain. You should check surrender charges and compare benefits carefully first, which is exactly what an Annuity X-Ray does.
Does it cost anything to work with you?
No. Your Annuity X-Ray, rate comparison and consultation are free. If you choose to buy an annuity, the insurance company pays the agent's commission; it is not deducted from a fixed annuity's value.
How do I get started?
Request a free annuity quote with the Get My Free Quote button at the top of this page, book a free 25-minute Annuity X-Ray, call (407) 974-7100, or download the free Annuity Rate Report to compare today's rates on your own first.
Plan. Protect. Prosper.
Know Exactly What Your Money Is Doing
Own an annuity? Get a free Annuity X-Ray. Shopping for one? Start with the free Annuity Rate Report. Either way, there is no cost and no obligation.
Prefer to talk now? Call (407) 974-7100