Orlando Medicare & retirement healthcare planning
Healthcare Planning in Florida for Retirees
Healthcare planning is retirement planning. We coordinate your Medicare decisions, IRMAA and tax strategy, long-term care preparation and retirement income into one clear plan, so healthcare costs are less likely to quietly erode what you worked decades to build.
✓ Medicare choices that fit your doctors, prescriptions and budget
✓ IRMAA-aware income planning to help avoid Medicare premium surcharges
✓ Long-term care planning before care starts, and help if it already has
15 minutes. No pressure, no obligation. Virtual or in person in Orlando.
Roger Fishel
Independent retirement planner. 20+ years helping Florida families retire with confidence.
20+ Years
Guiding Florida retirees and pre-retirees
Independent
Not tied to one insurance company
$0
Cost for your healthcare planning session
FL & Nationwide
In person in Orlando or by video
Healthcare Planning Basics
What Is Retirement Healthcare Planning?
Short answer: Retirement healthcare planning means choosing the right Medicare coverage, budgeting for premiums, prescriptions and out-of-pocket costs, managing your income so you avoid IRMAA surcharges, and preparing for long-term care, all as part of your retirement income plan.
In Florida, Medicare rules, income brackets, provider networks and long-term care costs directly affect your retirement income strategy. Without coordination, healthcare expenses can quietly erode what you worked decades to build.
At Roger Fishel Financial, we help individuals and couples in Orlando and throughout Florida align Medicare decisions, tax planning, long-term care preparation and retirement income into one coordinated plan built for long-term confidence.
Why it matters
Healthcare Can Quietly Drain the Retirement You Built
Medicare choices, IRMAA surcharges and long-term care costs do not show up one at a time. Each one affects your taxes, your income and the rest of your plan, so they need to be planned together.
Medicare choices
The wrong plan or a missed deadline can mean higher costs, doctors out of network and lifelong late penalties.
IRMAA surcharges
A Roth conversion or a large withdrawal can raise your Medicare premiums two years later if it is not timed with your income plan.
Long-term care
Medicare pays for very little ongoing care. Without a plan, care bills can drain savings and put the healthy spouse at risk.
Watch · Healthcare Costs in Retirement
How Much Does Healthcare Cost in Retirement in Florida?
Healthcare expenses are often underestimated. When they are layered together, healthcare can become one of the largest budget categories in a Florida retirement. Florida retirees should plan for:
✓ Medicare Part B premiums, and IRMAA surcharges at higher incomes
✓ Medicare Supplement or Medicare Advantage costs
✓ Prescription drugs and out-of-pocket deductibles
✓ Long-term care and home healthcare in Orlando and Central Florida
Proper planning makes these expenses predictable and sustainable inside your retirement income strategy.
The Florida retirement cost breakdown →2026 Numbers
2026 Medicare Costs Every Florida Retiree Should Know
These are the core Medicare costs to build into your retirement budget this year.
| Cost | 2026 amount | What it means for you |
|---|---|---|
| Part B standard premium | $202.90 a month | Usually deducted from your Social Security check. |
| Part B deductible | $283 a year | Paid before Part B starts covering doctor and outpatient care. |
| Part A hospital deductible | $1,736 per benefit period | Can apply more than once a year. Many Medicare Supplement plans cover it. |
| Part D out-of-pocket cap | $2,100 a year | The most you pay for covered prescriptions in 2026. |
| IRMAA starting point | Above $109,000 single or $218,000 joint (2024 income) | Part B rises to $284.10 a month or more, plus a Part D surcharge. |
Sources: Centers for Medicare & Medicaid Services and Social Security Administration, 2026. Want to lower these costs? Compare Medicare Supplement quotes.
What we coordinate
One Plan for Medicare, IRMAA, Long-Term Care and Income
Most people handle these one at a time, with different people. We bring them together, so every healthcare decision is checked against your taxes and your retirement income.
Medicare
Medicare Strategy and Plan Coordination
Medicare is not one-size-fits-all, and your choices directly affect retirement cash flow. We help Florida residents evaluate:
✓ Original Medicare vs. Medicare Advantage
✓ Medicare Supplement options in Orlando and surrounding counties
✓ Prescription drug coverage alignment
✓ Provider network access in Central Florida
✓ Enrollment timing and penalty avoidance
IRMAA
IRMAA Planning and Income Coordination
Higher-income retirees can pay Income-Related Monthly Adjustment Amount surcharges on Medicare premiums, based on income from two years earlier. We help you:
✓ Understand the IRMAA brackets
✓ Time Roth conversions strategically
✓ Manage taxable income during retirement
✓ Plan withdrawals to help minimize premium increases
✓ Avoid unintended Medicare cost spikes
Long-term care
Long-Term Care Planning in Florida
Long-term care is one of the biggest financial risks in retirement, and Medicare pays for very little of it. It covers short skilled nursing stays after a qualifying hospital stay, up to 100 days, but not ongoing custodial care. We look at:
✓ Asset protection strategies tailored to your situation
✓ Protecting the healthy spouse’s income and the family home
✓ Hybrid life insurance and annuity options with long-term care benefits
✓ Home care and facility cost projections in Orlando and Central Florida
Income
Healthcare and Retirement Income Integration
Healthcare cannot be separated from retirement income planning. Your plan must account for healthcare inflation, Medicare premiums and long-term care exposure. We integrate:
✓ Social Security timing decisions
✓ Sequence of returns risk analysis
✓ Tax-efficient withdrawal strategies
✓ Required minimum distribution coordination
✓ Healthcare budgeting inside your retirement income projections
Long-Term Care · Two Ways We Help
Before Care Starts or After It Begins, We Can Help
Most families don’t think about long-term care until a fall, a diagnosis or a hospital stay forces the issue. Whether you are planning ahead or facing a care need right now, there are ways to protect what you have built.
Plan ahead
Long-Term Care Pre-Planning
Done before you need care, while you are still healthy. The goal is to protect assets ahead of time. Traditional long-term care insurance is often very expensive, so we rarely use it here. Instead we use other strategies, tailored to your situation, to help shield what you have built.
✓ You are healthy and want a plan before care is ever needed
✓ You want to protect your home and savings for a spouse or children
✓ Long-term care insurance is too costly, or you may not qualify
Care has already started
Long-Term Care Crisis Planning
Done after care has already started. The options are different and more limited at that point, but there are still legitimate ways to help protect assets and help qualify for benefits. It is not too late to get help, and the sooner we are involved, the more options you have.
✓ A spouse or parent just entered a nursing home or assisted living
✓ A hospital or rehab discharge planner mentioned Medicaid
✓ Monthly care bills are draining your savings
We help clients with both. The earlier we’re involved, the more choices you have.
Talk With Roger About Long-Term CareFree and confidential. Facing a care decision this week? Call (407) 974-7100.
Who We Help
Who We Help With Healthcare Planning in Orlando
Whether we meet virtually or in person in the Orlando area, our focus is coordination and clarity.
Pre-Retirees
Within 10 years of retirement and planning Medicare, income and taxes together.
Newly Retired Floridians
Settling into Florida and choosing coverage that fits local doctors and hospitals.
Snowbirds
Coordinating coverage and care between Florida and a second home state.
High-Income Retirees
Concerned about IRMAA surcharges on Part B and Part D premiums.
Couples Enrolling Together
Timing two Medicare enrollments and protecting the surviving spouse.
Families Facing a Care Need
A spouse or parent needs care now, or soon, and you want to protect what you have built.
How it works
Your Healthcare Plan in Three Steps
1
Review
A free 15-minute session. We review your current coverage, doctors, prescriptions, income and timeline, in person in Orlando or by video.
2
Coordinate
We match Medicare, IRMAA, long-term care and income decisions into one plan and show you the costs and trade-offs.
3
Adjust every year
Medicare plans, premiums and tax rules change every year. We review your plan so it stays on track.
No cost, no pressure and no obligation to change anything.
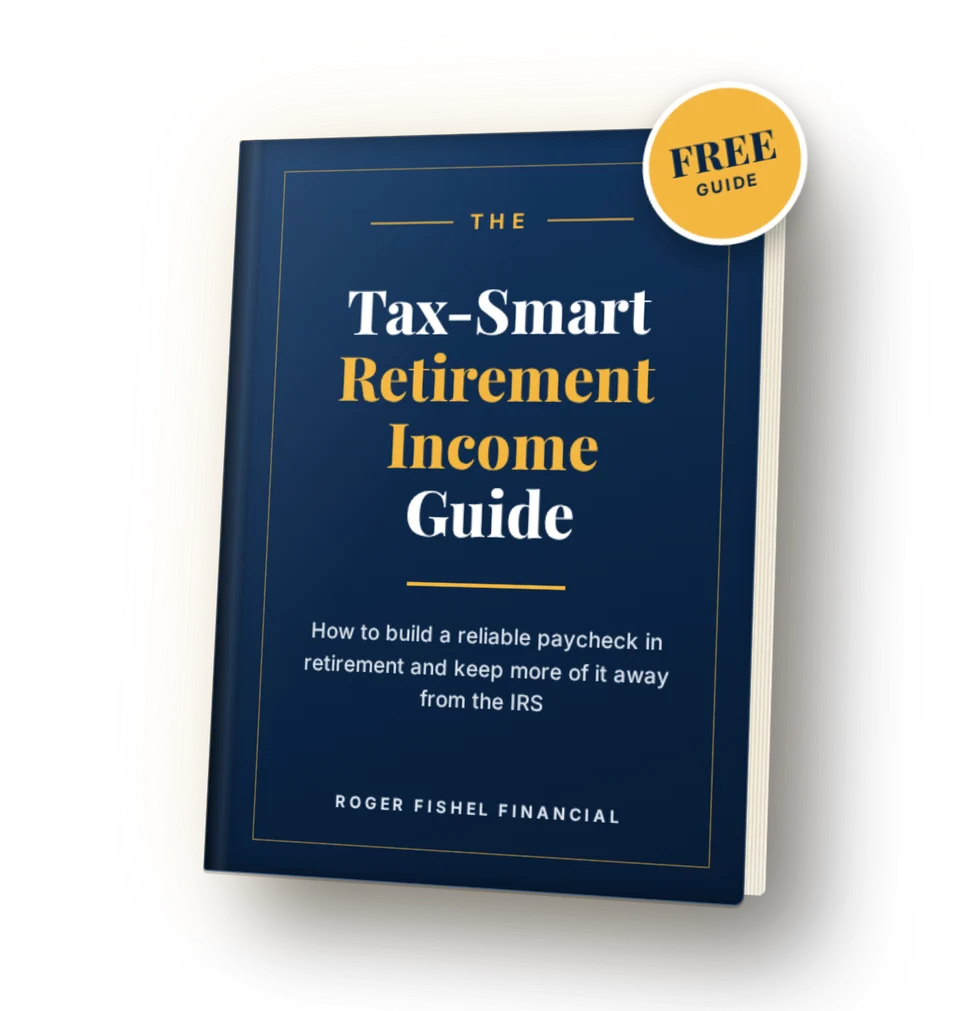
Not ready to talk yet?
Turn Your Savings Into a Retirement Paycheck That Lasts
Learn how to draw income from your 401(k), IRA and Social Security in the right order, so you may keep more of what you saved.
✓ The withdrawal order most retirees get backwards
✓ When a Roth conversion may make sense
✓ How to avoid a surprise tax bill in your first year
Free Resources
Florida Medicare and Healthcare Planning Guides
Plain-English articles from Roger Fishel on the healthcare questions Florida retirees ask most.
IRMAA: The Hidden Medicare Surcharge
The 2026 brackets, the two-year lookback and how to avoid surprise premium increases.
Read the guide →Medicare Supplement vs. Medicare Advantage in Florida
Why many Orlando retirees choose Medigap, and when Advantage can make sense.
Read the guide →How to Choose the Right Medicare Plan in Florida
A step-by-step guide to comparing Medicare coverage in Orlando.
Read the guide →Retiring Before 65 in Central Florida
How to bridge the health insurance gap until Medicare starts.
Read the guide →Long-Term Care Planning in Central Florida
Protecting your assets before care starts and after it begins.
Read the guide →The Fall 2026 Open Enrollment Guide
Medicare Annual Enrollment and ACA Marketplace deadlines for retirees.
Read the guide →
Frequently Asked Questions
Florida Healthcare Planning FAQs
Common questions we answer about healthcare and Medicare planning for Florida retirees.
How does Medicare work in Florida?
Medicare in Florida includes Original Medicare, Medicare Advantage plans and Medicare Supplement policies. Plan availability and provider networks vary by county, including Orange, Osceola, Polk and Seminole counties around Orlando.
When should I sign up for Medicare in Florida?
Most people should enroll during their Initial Enrollment Period, the 7 months that begin 3 months before the month you turn 65. If you are still covered by an employer plan through a company with 20 or more employees, you may be able to delay Part B without penalty and use a Special Enrollment Period later. Missing your window can mean lifelong late penalties.
What does Medicare cost in 2026?
In 2026 the standard Part B premium is $202.90 a month with a $283 annual deductible, the Part A hospital deductible is $1,736 per benefit period, and Part D out-of-pocket drug costs are capped at $2,100 a year. Higher-income retirees pay more through IRMAA, which begins above $109,000 of income for single filers and $218,000 for married couples, based on your tax return from two years earlier.
Are Medicare plans different in Orlando compared to other states?
Yes. Medicare Advantage plans and provider networks are county based. Plans available in Orlando may differ from those in other Florida counties or other states.
What is IRMAA and how can I avoid it?
IRMAA is a Medicare premium surcharge for higher-income retirees. Strategic income planning, including Roth conversion timing and withdrawal coordination, can help manage or reduce these surcharges.
How much should I budget for healthcare in retirement in Florida?
Healthcare budgets vary based on income, plan selection and long-term care exposure. Florida retirees should account for Medicare premiums, prescription costs, supplemental coverage and potential long-term care expenses.
Is long-term care insurance necessary in Florida?
Long-term care insurance is not required, and traditional policies are often very expensive or hard to qualify for, so we rarely use it. For most clients we use other strategies, tailored to their situation, such as asset protection planning and hybrid life insurance or annuities with long-term care benefits.
What is the difference between long-term care pre-planning and crisis planning?
Pre-planning happens before you need care, while you are still healthy, so there is time to protect assets ahead of time. Crisis planning starts after care has already begun. The options are more limited then, but there are still legitimate ways to help protect assets and qualify for benefits. We help with both, and the earlier we are involved, the more choices you have.
Is it too late to protect assets if a loved one is already in a nursing home?
Not necessarily. Even after care has started, there may still be legitimate ways to help protect savings and help a spouse or family member qualify for benefits. Every situation is different, and the sooner we look at it, the more options you are likely to have.
How can I get health insurance if I retire before 65 in Florida?
Common options include COBRA from your former employer, coverage through a working spouse’s plan, or an ACA Marketplace plan, where premium tax credits depend on your income. Managing your taxable income in the years before Medicare can lower your Marketplace premiums, so healthcare and withdrawal planning should be coordinated.
Do you offer virtual and in-person meetings in Orlando?
Yes. We work with Florida residents both virtually and in person in the Orlando area. Meetings are structured around your comfort and convenience.
Is healthcare planning included in retirement planning?
Healthcare planning is a core part of retirement planning. Medicare decisions, tax strategy and long-term care preparation must be integrated into your retirement income plan.
Did not see your question? Schedule a free 15-minute virtual strategy session.
Schedule a Free Q&A Strategy SessionPlan. Protect. Prosper.
Schedule Your Florida Healthcare Planning Session
Healthcare decisions affect your income, taxes and long-term financial security. If you live in Orlando or anywhere in Florida, let us coordinate your Medicare, long-term care and retirement income strategy into one clear plan.
Book My Free Clarity SessionPrefer to talk now? Call (407) 974-7100