Free 2026 claiming guide · Orlando & nationwide by video
Social Security Optimization: Get Your Claiming Decision Right
When you claim Social Security is a permanent decision that can be worth $100,000 or more over your lifetime, and much more for a married couple. Start with our free 2026 guide and see your options side by side before you file.
✓ What every age from 62 to 70 can pay you, for life
✓ How to protect your spouse’s survivor check
✓ The 7 costly claiming mistakes to avoid
Free 24-page PDF, updated for 2026. Every review with Roger is free too.
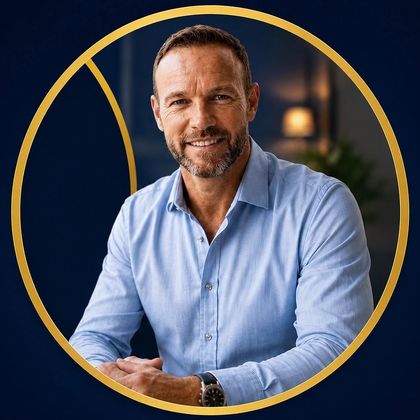
Roger Fishel
Independent retirement planner. 20+ years helping Florida families retire with confidence.
20+ Years
Guiding Florida retirees and pre-retirees
Independent
Advice built around you, not one product
$0
Cost for your Retirement Clarity Session
FL & Nationwide
In person in Orlando or by video
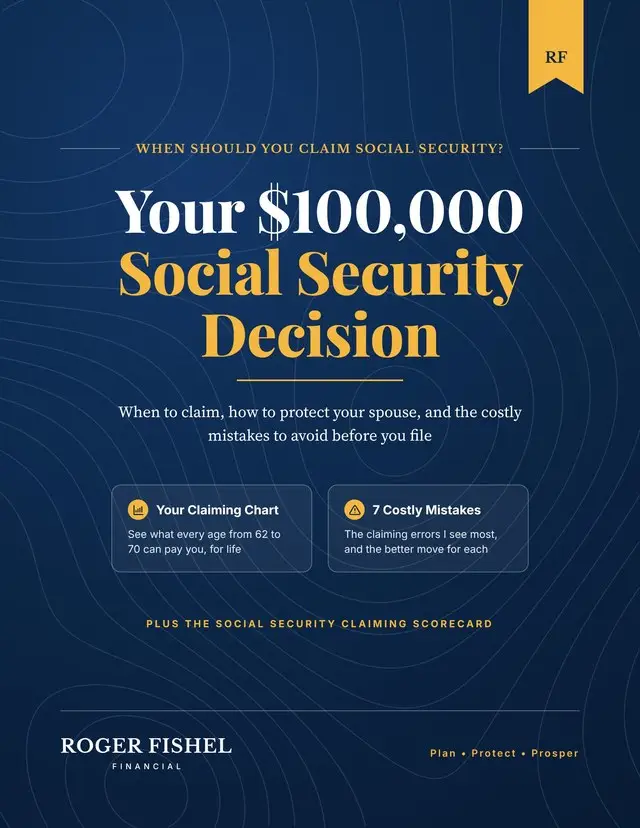
Free 2026 guide
When Should You Claim Social Security? Read This Before You File
For many people it is a $100,000 decision, and once you file it is mostly locked in for life. Our free 24-page guide, Your $100,000 Social Security Decision, puts the numbers side by side.
✓ Your claiming age chart, from 62 to 70
✓ The break-even trap, and the better question to ask
✓ A 10-point scorecard and a worksheet for your own numbers
Social Security basics
What Is Social Security Optimization?
Short answer: Social Security optimization is choosing when and how you (and your spouse) claim benefits so your household may receive the most lifetime income after taxes, with the strongest protection for whoever lives longer. It weighs your claiming age, spousal and survivor rules, taxes, Medicare premiums and your other savings together.
You can claim any month from 62 to 70, and every year you wait past full retirement age raises your check by 8 percent for life. That sounds simple until you add a spouse, a pension, a tax bracket and a retirement date. That is where most people get stuck, and where a second set of eyes can pay for itself many times over.
What age should you collect Social Security? →
Why you shouldn't decide alone
The Most Expensive Retirement Decision Most People Make by Themselves
Most people pick a claiming age at the kitchen table, or at the Social Security office, with no one looking at the whole picture. The numbers show how often that goes wrong.
4%
of retirees claimed at the age that would have given them the most lifetime income, in a study of real retiree data.
$111,000
in estimated lifetime income lost, on average, by households that claimed at the wrong time.
9,000+
possible combinations of claiming months for a married couple, before taxes and Medicare enter the picture.
12 months
is the only window to undo your claim, and you must pay back every dollar you received.
The good news: the right strategy is not a guess. It can be modeled in advance with your real numbers, and the review is free.
Get the Free Claiming GuideSources: United Income study of Social Security claiming (2019); Social Security Administration.
Try it yourself
See What Waiting Could Mean for Your Monthly Check
Move the sliders to compare claiming at 62, 67 or 70 and see how long you would need to live for waiting to pay off. It takes about 30 seconds, and nothing you enter is saved or sent anywhere.
Free tool
Claiming Age Calculator
Not sure? Find your estimate in your free my Social Security account.
Plan for income to age
Claim at 67
$2,000 a month
100% of your full retirement age benefit, for life
Estimated total to age 90
$552,000
Compared with claiming at 62
+$81,600
Break-even age: 78 years, 8 months
Estimated lifetime benefits by claiming age
If you live to 90, claiming at 70 pays the most in this example.
This is the simple version, for one person. Your real answer also depends on your spouse, survivor benefits, taxes and Medicare premiums. The free 2026 guide walks you through all of it, with a worksheet for your own numbers.
Get the Free Claiming GuideOr book a free personalized reviewHypothetical example for education only. Uses Social Security rules for people born in 1960 or later (full retirement age 67), whole-year claiming ages and today’s dollars, with no cost-of-living increases, taxes, earnings limits or spousal benefits. It is not a prediction of your benefits.
This calculator also has its own page: Social Security Break-Even Calculator, with break-even ages explained.
Compare Your Options
Claim at 62, 67 or 70? How the Ages Compare
Every year you wait between 62 and 70 raises your monthly check for life. Here is what changes at each age if you were born in 1960 or later, when full retirement age is 67.
Earliest Option
Claim at 62
Income starts right away, but your monthly benefit is permanently reduced by up to 30 percent.
✓ Income starts as soon as you need it
✓ Can make sense with serious health concerns
✓ Lets other savings stay invested longer
Watch out: The reduction is permanent, it can shrink your spouse's survivor benefit, and if you are still working the earnings limit can withhold benefits.
Full Retirement Age
Claim at 67
You receive 100 percent of the benefit you have earned, with no earnings limit once you reach this age.
✓ Full benefit with no early filing reduction
✓ Work as much as you want with nothing withheld
✓ Keeps spousal and survivor options flexible
Watch out: It feels like the safe middle, but it is not automatically the best choice until you run your numbers.
Maximum Benefit
Delay to 70
Your benefit grows about 8 percent for each year you wait past full retirement age, reaching roughly 124 percent of your full benefit.
✓ Largest guaranteed, inflation-adjusted check for life
✓ Strongest survivor benefit for your spouse
✓ Opens a window for Roth conversions before benefits begin
Watch out: You need a plan to cover your income from other savings while you wait, ideally in a tax-smart order.
The best age is personal. Your review shows your break-even ages and lifetime income for each option side by side, so the choice becomes clear.
Read: 5 Big Social Security Benefit Changes in 2026 →Beyond the calculator
What a Calculator Can’t See
Online calculators look at one person and one number. Your real answer depends on how Social Security fits with everything else. These are only some of the factors we look at, and the right mix depends on your situation.
Your spouse’s check
For married couples, the higher earner’s claiming age usually sets the survivor’s income for the rest of their life. That one choice can protect, or shrink, the check that lasts.
Taxes on your benefits
Benefits can start to be taxed once your “provisional income” passes $25,000 for singles or $32,000 for married couples, and up to 85 percent can be taxable. Those limits have never been raised for inflation.
Medicare premiums (IRMAA)
Your income from two years earlier sets your Medicare Part B and D premiums. A large withdrawal or conversion at the wrong time can raise them.
The Roth conversion window
The years between retiring and claiming can be a lower-tax window to convert savings, if your plan covers income while you wait. Roth conversions are taxable in the year of conversion and may not be appropriate for everyone.
Working while collecting
Claim before full retirement age while still working, and the earnings test can temporarily withhold part of your benefit.
Your health and family history
How long you live is the biggest unknown. A good plan works if you live a long time and still protects your spouse if one of you lives much longer.
Free and no obligation. Neither the firm nor its agents or representatives may give tax or legal advice.
Couples, widows and divorcees
Spousal, Survivor and Divorced Spouse Benefits
Married, widowed and divorced retirees often have more options than they realize. Coordinating them correctly can change your household income for decades.
Spousal benefits
A spouse can receive up to 50 percent of the higher earner’s full retirement age benefit. Claiming before full retirement age reduces it.
Survivor benefits
The surviving spouse keeps the larger of the two checks, which is why the higher earner’s claiming age is often the most important decision a couple makes.
Divorced spouse benefits
If your marriage lasted at least 10 years and you have not remarried, you may be able to claim on your former spouse’s record without reducing their benefit.
Widows and widowers
Survivor benefits can start as early as 60, and the order you take your own and your survivor benefit can matter.
Taxes and Medicare
How Social Security Connects to Your Taxes and Medicare
When you claim changes more than your monthly check. It also changes how much of it is taxed, what you pay for Medicare and when a Roth conversion makes sense.
Up to 85% Can Be Taxed
Florida does not tax Social Security, but the IRS can. If half your benefits plus your other income is over $25,000 (single) or $32,000 (married filing jointly), part of your benefits becomes taxable, up to 85%. Those limits are not adjusted for inflation.
Try the Tax Bomb Calculator →Social Security and IRMAA
Medicare sets your Part B and Part D premiums from your income two years earlier, and the taxable part of your benefits counts. One big withdrawal or home sale can raise your premiums for a year.
Read: How IRMAA works →The Roth Conversion Window
The years after you stop working and before Social Security and RMDs begin are often your lowest-income years. Converting some IRA money to a Roth then may lower the tax on your benefits and RMDs later.
Plan the timing with Roger →Working While You Collect
Before full retirement age, $1 of benefits is withheld for every $2 you earn above $24,480 (2026). The limit rises in the year you reach full retirement age and disappears after that, and withheld benefits are credited back later.
Read: 10 Social Security mistakes →Protect the Survivor
When one spouse dies, the survivor keeps the larger of the two benefits. That is why the higher earner waiting to claim can raise the income a widow or widower lives on for life.
Read: The widow's tax trap →The Yearly COLA
Benefits rise each January with inflation, and the new amount is announced in October. Medicare Part B premiums usually come out of your check, so a higher premium can take part of the raise.
Social Security break-even calculator →We help retirees in Orlando, Tampa and across Florida coordinate Social Security with taxes and Medicare, in person in Central Florida or by video.
Get a Free Social Security Review
Roth conversions are taxable in the year of conversion and may not be appropriate for everyone. Neither the firm nor its agents or representatives may give tax or legal advice.
What's new
Social Security Changes for 2026 You Should Know
The rules keep moving. Here is what changed recently and how it may affect your claiming decision.
A 2.8% raise in 2026
Benefits rose 2.8 percent in January 2026. The 2027 cost-of-living increase is announced in October, and we update our clients’ plans when it lands.
Higher earnings limits
Before full retirement age, $1 is withheld for every $2 you earn above $24,480. In the year you reach it, $1 for every $3 above $65,160.
WEP and GPO are gone
The Social Security Fairness Act ended the Windfall Elimination Provision and Government Pension Offset. Some teachers, police officers, firefighters and other public employees now qualify for more.
A new $6,000 senior deduction
From 2025 through 2028, people 65 and older may deduct an extra $6,000 each, phasing out above $75,000 of income ($150,000 married). It can lower the tax you pay on your benefits and other income.
The trust fund outlook
The 2026 Trustees Report projects full benefits until late 2032, then about 78 percent payable unless Congress acts. That is a reason to plan with a margin of safety, not to panic.
Paper checks are ending
The Treasury began phasing out paper checks on September 30, 2025. Benefits now arrive by direct deposit or a Direct Express card, with limited exceptions.
Sources: Social Security Administration, 2026 Social Security and Medicare Trustees Report, IRS, U.S. Treasury. Current as of October 2026. Neither the firm nor its agents or representatives may give tax or legal advice.
Avoid Costly Errors
Common Social Security Mistakes We Help Retirees Avoid
Most claiming mistakes are permanent. These are the ones we see most often with Orlando and Central Florida retirees.
01
Claiming at 62 Without Running the Numbers
Filing early because you can, not because it fits your plan, can lock in a smaller check for the rest of your life.
02
Ignoring Taxes on Your Benefits
Up to 85 percent of your benefits can be taxed at the federal level depending on your other income. Florida has no state income tax, but the IRS still counts.
03
Overlooking the Survivor Benefit
When one spouse passes, the smaller check stops. The higher earner's claiming age often decides how much the surviving spouse lives on.
04
Missing Spousal or Divorced Spouse Benefits
Many people never learn they qualify for a benefit based on a current or former spouse's work record.
05
Working While Collecting Early
Claim before full retirement age while still working, and the earnings limit can temporarily withhold part of your benefits.
06
Not Coordinating With Medicare and IRMAA
Social Security, IRA withdrawals and Roth conversions all affect your Medicare premiums. Timing them together matters.
How it works
Your Free Social Security Review in Three Steps
1
Book a free call
Tell us when you hope to retire, whether you are married and what worries you most. Virtual or in person in Orlando.
2
We run your numbers
We model every realistic claiming age for you and your spouse, including taxes, Medicare premiums and survivor income, and show the trade-offs side by side.
3
Claim with confidence
You get a clear recommendation in plain English and help when it is time to file. We revisit it as your life and the rules change.
Rather ask a question first? Request information and Roger will get back to you.
Watch
Social Security Mistakes, Explained in Plain English
Short videos from Roger on the Social Security mistakes he sees retirees make most, and how to avoid them.
Free resources
Social Security Guides for Florida Retirees
Plain-English articles from Roger Fishel on the Social Security questions we hear most.
What Age Should You Collect Social Security?
The pros and cons of 62, full retirement age and 70 for Orlando retirees.
Read the guide →5 Big Social Security Changes in 2026
The new numbers and rules that affect your benefits this year.
Read the guide →10 Social Security Mistakes Retirees Make
The most common, and most permanent, claiming errors we see.
Read the guide →How to Calculate Your Social Security Benefit
How your benefit is figured, and how to check your earnings record.
Read the guide →Should You Work Part-Time in Retirement?
How a part-time income can let you delay Social Security.
Read the guide →The Widow’s Tax Trap
Why a surviving spouse’s taxes can jump, and how to plan ahead.
Read the guide →
Frequently Asked Questions
Social Security Optimization FAQs
Straight answers to the Social Security questions we hear most from Florida retirees and pre-retirees.
What is the best age to claim Social Security?
There is no single best age for everyone. You can claim as early as 62, at full retirement age (67 for anyone born in 1960 or later) or as late as 70. The right age depends on your health, other income, tax bracket and whether you are married. We compare every option using your real numbers.
Is Social Security taxed in Florida?
Florida has no state income tax, so the state does not tax your benefits. At the federal level, up to 85 percent of your benefits can be taxable depending on your other income. Smart withdrawal planning and Roth conversions can help reduce that.
Does Social Security count toward IRMAA?
Yes, it can. Medicare sets your Part B and Part D premiums from your modified adjusted gross income two years earlier, and the taxable part of your Social Security benefits is included in that income. A large IRA withdrawal, Roth conversion or home sale in the same year can push you over an IRMAA threshold, so we plan those around your Social Security start date.
Will Social Security run out of money?
No. The 2026 Social Security Trustees Report projects that the retirement trust fund can pay full benefits until late 2032. After that, incoming payroll taxes would still cover about 78 percent of scheduled benefits unless Congress acts. That is a reason to plan with a margin of safety, not a reason to panic.
Should I claim early in case benefits are cut?
Fear of cuts is one of the most common reasons people file early, but it deserves a second look. Under current law, a shortfall would reduce benefits for retirees whether they claimed at 62 or 70, while the early filing reduction is permanent. We can model both scenarios so you can decide with real numbers.
Can I work and collect Social Security at the same time?
Yes. In 2026, if you are under full retirement age, $1 is withheld for every $2 you earn above $24,480. In the year you reach full retirement age, $1 is withheld for every $3 above $65,160. Those benefits are not lost, because your monthly amount is recalculated at full retirement age. Once you reach full retirement age, there is no earnings limit.
How do spousal and survivor benefits work?
A spouse may receive up to 50 percent of the higher earner’s full retirement age benefit. When one spouse passes, the survivor keeps the larger of the two benefits. Because of this, the timing of each spouse’s claim can make a large difference in lifetime household income.
Did the Social Security Fairness Act change my benefits?
It may have. The law, signed in January 2025, ended the Windfall Elimination Provision and the Government Pension Offset. If you have a pension from work that did not pay into Social Security, such as some teachers, police officers, firefighters and other public employees, your own benefit or your spousal or survivor benefit may now be higher. We can review your statement with you.
Can I change my mind after I claim?
Within 12 months of first claiming, you can withdraw your application once by repaying the benefits you received. After full retirement age, you can also voluntarily suspend benefits to earn delayed retirement credits up to age 70. Because your options are limited, it pays to get the decision right the first time.
What should I bring to my Social Security review?
Your Social Security statement from ssa.gov (and your spouse’s), a recent tax return and a general list of your savings and income sources. If you do not have everything, that is fine. We can start with what you have.
Is the Social Security review really free?
Yes. The review is complimentary with no cost and no obligation. You will walk away with clarity on your options whether or not we work together.
Did not see your question? Ask Roger in a free review.
Get the Free Claiming GuidePlan. Protect. Prosper.
Don’t Leave Your Biggest Retirement Decision to Guesswork
Start with the free 2026 guide. See what every age from 62 to 70 can pay you and how to protect your spouse, before you file.
Send Me the Free GuidePrefer to talk it through? Book a free Social Security review or call (407) 974-7100.