Orlando, Central Florida & nationwide by video
Florida has no state income tax, but the IRS still takes a share of every IRA and 401(k) dollar you withdraw. We coordinate your withdrawals, Roth conversions, Social Security and Medicare so you may pay less over your lifetime, not just this year.
Always free. No pressure, no obligation. Virtual or in person in Orlando.
Retirement tax planning basics
Most people spend 30 years saving in tax-deferred accounts. Very few have a plan for the day those dollars come out. A tax return looks back at last year. A tax plan looks forward 10, 20 and 30 years.
Neither the firm nor its agents or representatives may give tax or legal advice. We work alongside your CPA or tax professional.
The window most retirees miss
When your paycheck stops, your taxable income often drops. Then Social Security starts, and at 73 or 75 the IRS requires withdrawals whether you need the money or not. For many retirees, taxes go up in their 70s.
Working years: high income, little room to move.
Early retirement: a short stretch where strategies like Roth conversions may cost less.
RMDs plus Social Security: income can climb into higher brackets and raise Medicare premiums.
The window is different for every household, and it closes. We map yours in your free session.
Find my tax windowHypothetical illustration for education only. Not based on any client.
Retirement tax planning in Florida
No state income tax is a great start. Federal taxes still reach most retirement income. These are some of the areas we look at, and the right mix depends on your situation.
At 73 (or 75 if born in 1960 or later) the IRS sets a minimum you must withdraw each year. Large RMDs can push you into a higher bracket.
We plan years aheadPaying tax now so future qualified withdrawals can be tax free. Timing and amount matter. Conversions are taxable in the year of conversion and may not be appropriate for everyone.
We model the numbersUp to 85% of your benefit can be taxable, depending on your other income. The order of your withdrawals can change how much.
We coordinate the orderHigher income can raise Part B and Part D premiums through IRMAA, based on your tax return from two years earlier. One large withdrawal can trigger it.
We watch the thresholdsAt 70½ or older, a qualified charitable distribution from your IRA can count toward your RMD without adding to your taxable income.
We match it to your givingAfter a spouse passes, the survivor often files as single on similar income, which can mean higher brackets and Medicare premiums.
We plan for both of you30-second self-check
Tap each statement that is true for you.
Tap the statements that fit you. Two or more usually means there is money on the table worth a closer look.
Quick reference
The thresholds that shape most retirement tax decisions. Knowing the number is step one. Knowing what to do about it is where planning comes in.
| Rule | 2026 number | Why it matters |
|---|---|---|
| Florida state income tax | 0% | No state tax on IRA, 401(k), pension or Social Security income. Federal tax still applies. |
| RMD starting age | 73 or 75 | 73 if born 1951 to 1959, 75 if born 1960 or later. Missed RMDs can carry a 25% penalty. |
| Social Security taxation | $25,000 / $32,000 | Provisional income above these levels (single / joint) makes up to 50%, then up to 85%, of benefits taxable. |
| Senior deduction | $6,000 | Extra deduction for people 65 and older from 2025 to 2028, phasing out above $75,000 / $150,000 of modified adjusted gross income. |
| Medicare IRMAA starts | $109,000 / $218,000 | Income above these levels (single / joint, from two years earlier) raises Part B and D premiums. |
| Qualified charitable distribution | Age 70½ | Give directly from your IRA; it can count toward your RMD without adding to taxable income. |
Sources: IRS, Social Security Administration and Medicare.gov, current as of 2026. Rules change, so confirm the details for your situation.
How it works
Tell us where your savings are and what worries you about taxes. In person in Orlando or by video from home.
We project your income, brackets, RMDs and Medicare premiums year by year, and show where the opportunities may be.
We share the plan with your CPA or tax preparer and review it each year as tax laws and your life change.
No cost, no pressure and no obligation to change anything.
Not ready to talk yet?
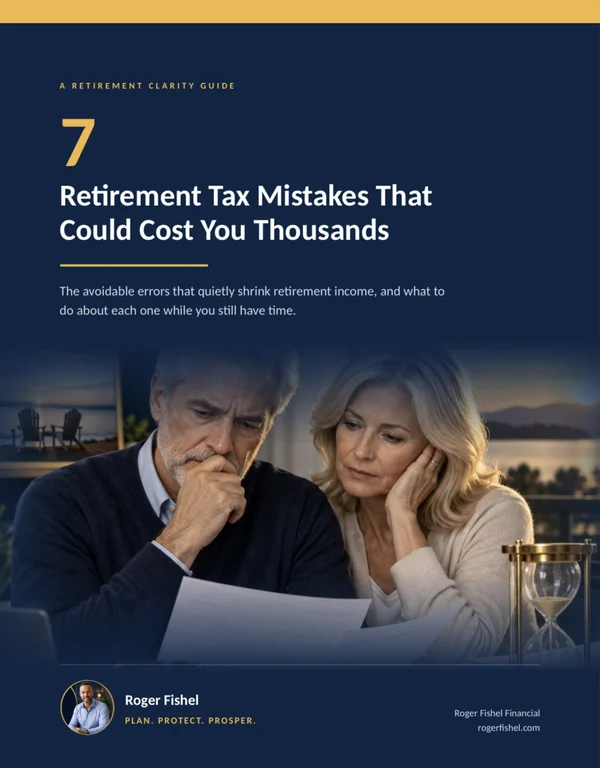
The most common and costly retirement tax errors we see, and what to do about each one while you still have time.
Free resources
Plain-English articles from Roger Fishel on the tax questions Florida retirees ask most.
How 401(k) withdrawals are taxed in retirement and ways that may defuse the bill.
Read the guideThe 2026 guide to when converting may make sense, and when it may not.
Read the guideHow a single large withdrawal can raise your Medicare premiums two years later.
Read the guideWhen required minimum distributions start, how they are figured and how to plan for them.
Read the guideWho qualifies for the new deduction for people 65 and older, and how to make the most of it.
Read the guideA Central Florida retiree's checklist before December 31.
Read the guide
Frequently asked questions
Straight answers to the tax questions we hear most from Florida retirees and pre-retirees.
No. Florida has no state income tax, so it does not tax Social Security, pensions or IRA and 401(k) withdrawals. Federal income tax still applies, and that is where most retirement tax planning happens.
It depends on your current tax bracket, your expected future bracket, how you will pay the tax and your plans for your heirs. Roth conversions are taxable in the year of conversion and may not be appropriate for everyone. We run the numbers with you before making a recommendation.
Ideally five to ten years before you retire. That gives you time to use lower income years wisely and avoid surprises when RMDs begin. Starting later still helps, and it is never too late to review your plan.
Yes, it can. Medicare uses your income from two years earlier to set Part B and Part D premiums. Income above the IRMAA thresholds adds a surcharge, so the size and timing of withdrawals and conversions matter.
We focus on tax planning, not tax preparation. We work alongside your CPA or tax preparer so your plan and your return stay coordinated. If you do not have a CPA, we can suggest a few to consider.
Three. The Tax Bomb Calculator estimates how much of your IRA or 401(k) may go to taxes. The Retirement Tax Calculator estimates your potential lifetime retirement taxes. The free guide, 7 Retirement Tax Mistakes That Could Cost You Thousands, explains the most common errors. All are free, with no obligation.
It is a relaxed conversation. We ask where your savings are held, when you plan to retire and what concerns you most, then point out a few areas that may be worth a deeper look. There is no cost and no obligation.
Yes. We meet in person in Orlando and Central Florida, and by video with individuals and couples across Florida and the rest of the country.
Did not see your question? Ask it in a free session.
Schedule a Free Q&A SessionFree Retirement Clarity Guide
7 Retirement Tax Mistakes That Could Cost You Thousands
Learn the avoidable errors that quietly shrink retirement income, and what to do about each one while you still have time.
✓ RMD, Roth and Social Security tax traps
✓ Simple fixes you can act on this year
✓ Sent to your inbox in seconds
By submitting, you agree to receive emails and text messages from Roger Fishel Financial. Msg and data rates may apply. Reply STOP to opt out. We never sell your information.